
Capital markets have always fueled innovation—but not always inclusion.
Larry Fink’s 2025 letter signals a potential turning point: a world where private markets, retirement income, and blockchain-based portfolios are no longer the preserve of the wealthy, but accessible to everyday investors. This post traces the evolution from exclusive coffee house trading to a future of tokenized investing—and why this shift matters for the next era of wealth creation.
1. The Origins: Capitalism Wasn’t Built for the Many
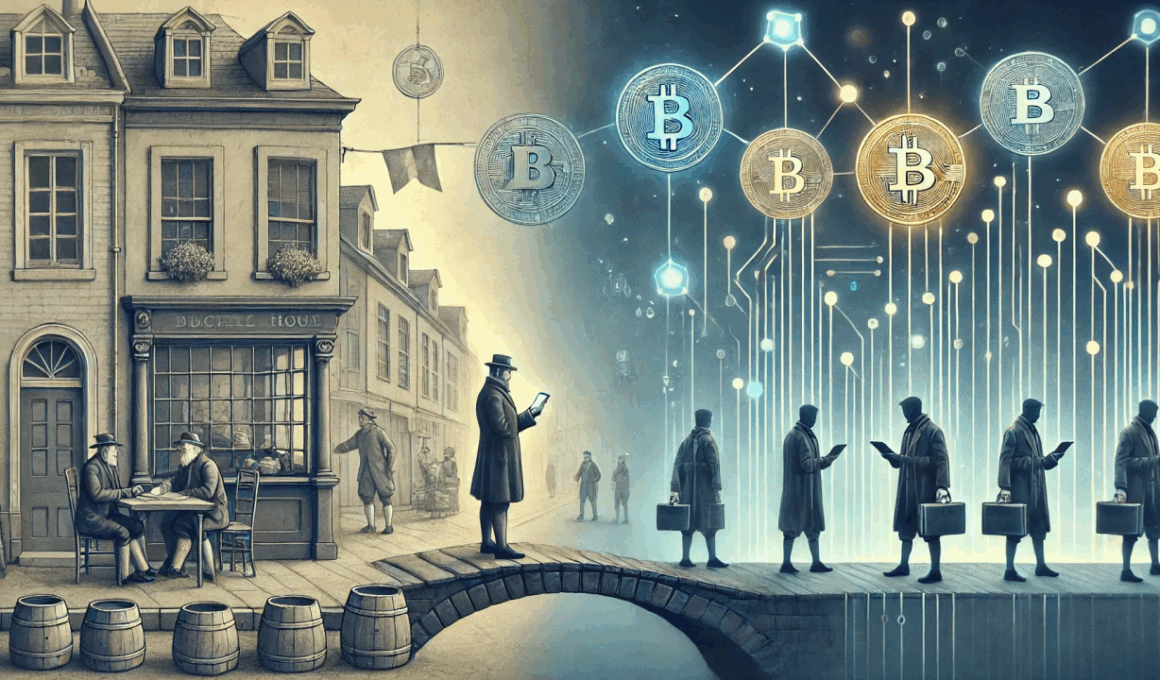
The world’s first stock exchange wasn’t on Wall Street—it was in a coffee house in Amsterdam, circa 1602.
The Dutch East India Company’s IPO created a new financial era, but not an inclusive one. Of 1,143 founding investors, 90% were wealthy merchants. Just two maids invested 50 guilders each—an early glimpse of how rare financial access truly was (Fink, 2025).
From London’s Jonathan’s Coffee House to Wall Street’s early days, capital markets were engineered by and for elites. Even by 1900, just 1% of U.S. households owned stocks. That number only rose with the spread of mutual funds and 401(k)s by the late 20th century.
But even today, the real wealth engine—private markets—remains largely locked behind institutional doors.
2. Public Markets Widened Access. Private Markets Didn’t.
For decades, investors clung to the 60/40 portfolio split: 60% stocks, 40% bonds. The assumption? That public markets provided enough diversification and return potential.
That assumption is now outdated.
Private equity, private credit, infrastructure—they’ve consistently outperformed public benchmarks. But high minimums, regulatory limits, and illiquidity kept retail investors out. The same inequality plagues retirement systems, where Social Security and defined-contribution plans often fall short.
The result? Market access expanded—but prosperity didn’t.
3. Fink’s 2025 Vision: Building a Truly Inclusive Investment System
In his latest letter, Larry Fink proposes a redesigned financial architecture: inclusive, tech-enabled, and geared for the future of wealth creation.
3.1 Unlocking Private Markets for All
BlackRock’s recent acquisitions—Global Infrastructure Partners, Preqin, HPS—aren’t just corporate plays. They’re strategic bets on making private markets retail-friendly.
Key pillars of this vision:
- Lowering investment minimums
- Increasing liquidity through secondary markets
- Enhancing transparency via better data (hello, Preqin)
- Adjusting regulation for retail suitability
Fink sees a world where owning a slice of a toll road or data center is as normal as holding an ETF.
3.2 The New Portfolio: 50/30/20
Forget 60/40. Fink suggests a modernized allocation:
- 50% public equities
- 30% bonds
- 20% private assets
This isn’t just a diversification play—it’s a philosophical shift toward real economy exposure and risk-adjusted alpha. Preqin’s analytics will support better pricing, benchmarking, and transparency for these previously opaque assets.
3.3 Tokenization: A Game-Changer for Retail Investors
The boldest piece of the puzzle? Tokenization.
By turning illiquid assets—like real estate, infrastructure, or private equity—into fractional digital tokens, investors can buy in with ease. Benefits include:
- Lower capital requirements
- Faster, cheaper settlement
- Real-time auditability and ownership tracking
- Integration with digital wallets and identity layers
Think: owning 0.0001% of a solar farm from your phone. This is financial inclusion via blockchain.
3.4 Rethinking Retirement: From Fragile to Future-Proof
The retirement crisis is real:
- 1 in 3 Americans has no retirement savings
- Gen X is alarmingly underprepared
- Social Security could be insolvent by 2035 (Fink, 2025)
BlackRock proposes a 3-pronged fix:
- Emergency savings with auto-enrollment
- “Baby bonds” to kickstart early investment
- LifePath Paycheck®, a product turning 401(k)s into guaranteed income streams
The goal? Shift retirement from a risk to a right.
4. Challenges Ahead: Don’t Confuse Access with Equity
Fink’s roadmap is ambitious—but not frictionless.
- Illiquidity & Complexity: Private assets can trap capital and confuse inexperienced investors.
- Regulatory Catch-Up: Tokenized assets may evolve faster than global frameworks.
- Inequality 2.0?: Expanding access doesn’t guarantee equal outcomes if financial literacy and capital gaps persist.
Without safeguards, “democratization” could become just another buzzword.
5. A New Era of Capitalism—If We Choose It
We’ve come a long way from Amsterdam’s merchant halls—but the mission is still unfinished.
True democratization of investing isn’t just about platforms or portfolios. It’s about equipping every individual—not just institutions—to participate in wealth creation.
That means:
- Smarter regulation
- Inclusive product design
- Continued innovation in fintech and tokenization
Capitalism doesn’t need to be dismantled—it needs to be rebalanced.
And the foundation for that shift is already being poured.
Follow for more on: tokenized assets, South African equity trends, private market innovation, and the future of retirement.
#Investing #Tokenization #PrivateMarkets #FinancialInclusion #RetirementReform #BlackRock #EmergingMarkets #WealthCreation #DigitalAssets
And the foundation for that shift is already being poured.
6. References
Merton, R.C., 1983. On the role of social security as a means for efficient risk sharing in an economy where human capital is not tradable. In: Z. Bodie and J.B. Shoven, eds. Financial Aspects of the United States Pension System. Chicago: University of Chicago Press, pp.325–358.
Bodie, Z., Kane, A. & Marcus, A.J., 2018. Investments. 11th ed. New York: McGraw-Hill Education.
Fink, L., 2025. The Democratization of Investing: Annual Chairman’s Letter to Investors. [online] BlackRock. Available at: https://www.blackrock.com/corporate/investor-relations/larry-fink-annual-chairmans-letter [Accessed 1 April 2025].
Markowitz, H., 1952. Portfolio selection. The Journal of Finance, 7(1), pp.77–91.